Chapter 4 - The House We Built
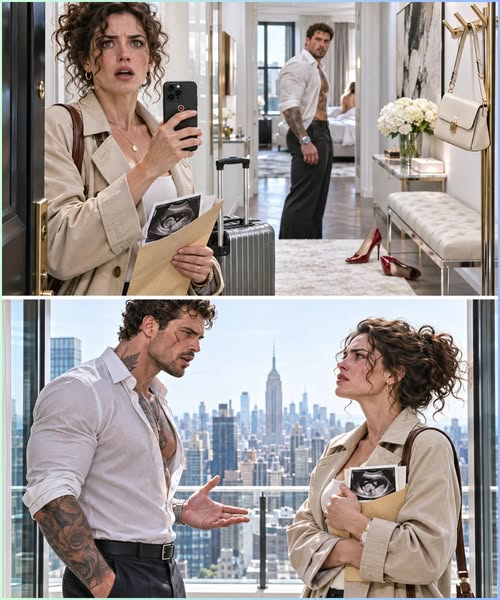
The woman at the bank transferred me to a lending specialist. I waited on hold while cheerful piano music played and the ultrasound photograph rested beside my phone. The juxtaposition was almost insulting. Somebody had designed that music for people whose lives were proceeding normally.
When the specialist finally answered, she confirmed that a home equity line of credit had been opened against our San Diego house three months earlier. The approved limit was four hundred and twenty thousand dollars. Nearly all of it had been drawn.
I asked her to repeat the number.
She did.
“I never applied,” I said.
The specialist's voice changed. She stopped offering routine explanations and began asking careful questions. Was I the joint owner? Had I approved electronic signatures? Had I recently authorized anyone to act for me?
“No. No. And no.”
She documented a dispute, restricted further draws pending review, and gave me a fraud department reference number. She warned me not to assume that an investigation would be immediate or simple. I appreciated that she did not promise a miraculous solution.
I knew the house's value. We had bought it six years earlier, when the neighborhood still had more repair shops than coffee bars. Our first summer, Lucas and I painted the living room ourselves, arguing about which white was actually white. We planted a lemon tree that had grown crooked because I kept forgetting to turn its pot. We rebuilt the back steps one Saturday at a time.
I could picture every wall. I could not picture a borrowed four hundred thousand dollars inside them.
Before making the call, I opened the folder of photographs I kept from our first year in the house. In one picture Lucas was kneeling beside a cabinet with a screwdriver between his teeth. In another he had fallen asleep on the bare living room floor after we'd spent all day hauling furniture through the heat. The house had never been a simple investment to me. It was where we ate noodles out of cardboard cartons when the kitchen wasn't finished, where my mother had recovered after surgery, where Tessa had slept on the couch when a relationship of hers ended badly. Even the water stains on the ceiling told stories I could still name. I went from picture to picture and felt anger replacing the shock. Lucas had borrowed against a place built from years of shared effort and then spoken about it as if it were a number he was authorized to move. I checked the deed in our closing binder to be sure my name was listed. It was. I also checked the last mortgage statement, the homeowner's insurance policy, and the app where we tracked repair costs. None mentioned the new credit line. Nothing in our household budgeting had prepared me for it. I wrote three questions on the back of the hotel stationery: Who signed? Where did the money go? How do I keep the house safe? I could not answer any of them, but I could ask them without apologizing.
I stared at the three questions until my eyes hurt. Then I pressed the call button. An answer would be better than another comfortable lie.
I called Lucas.
He answered before the second ring. “Finally.”
“What's the loan?”
Silence.
“Lucas.”
“What loan?”
“The home equity line. Four hundred and twenty thousand.”
He drew a breath. “Mere, listen to me.”
“You said nothing was urgent.”
“It's a bridge facility. It will be paid back.”
“I didn't sign for it.”
“You agreed we might use the house for the investment.”
“We discussed refinancing to lower our mortgage rate. We didn't discuss borrowing the price of another house.”
“Please don't get dramatic.”
I looked around the sterile hotel room. “You borrowed against our home without telling me. Describe the correct level of drama.”
He spoke faster. The money was temporary, he said. His partners had structured a small development fund. A closing had moved unexpectedly. He had to cover a gap for a matter of weeks. Everyone would be made whole.
“Who is everyone?” I asked.
“Investors.”
“Names, Lucas.”
“Not over the phone.”
“Then send the documents.”
“I can't share confidential business records.”
“They're records secured by my house.”
He changed direction. “You shouldn't be making a bank complaint without talking to me first.”
The sentence confirmed what the affair hadn't: his instinct was to protect the arrangement, not the person standing beneath it.
“Did you sign my name?”
“I handled the paperwork. We can discuss details when I get home.”
I ended the call. The hotel room seemed to tilt. I set the phone down, waited for my pulse to settle, and called Tessa again.
Her reaction was practical. “You need a lawyer who handles both divorce and financial fraud. And maybe somebody who knows what happens when a husband uses his wife's identity.”
“I know.”
“I'm going to research, but you make the calls. I won't take over.”
I loved her for that. People often mistake support for the right to control. My sister offered a handhold instead of a steering wheel.
By afternoon I had an appointment with Naomi Sloane, a family-law attorney recommended by a colleague. I booked a flight home for the following morning. I also asked the bank to preserve any application records and electronic signing logs connected to the loan.
Before packing, I studied the ultrasound again. The tiny curve on the image seemed like a private promise. I had wanted to build a nursery in the room facing the lemon tree. That dream now had a legal problem attached to it, along with a husband who had placed another woman's shoes in our second home.
Lucas sent six texts that evening. Four asked me to call. One told me I was overreacting. The last read: Please don't tell the bank I forged anything. You don't understand what's at stake.
May you like



I stared at it a long time.
I had not used the word forged. He had.







