Chapter 18 - The Countertrap
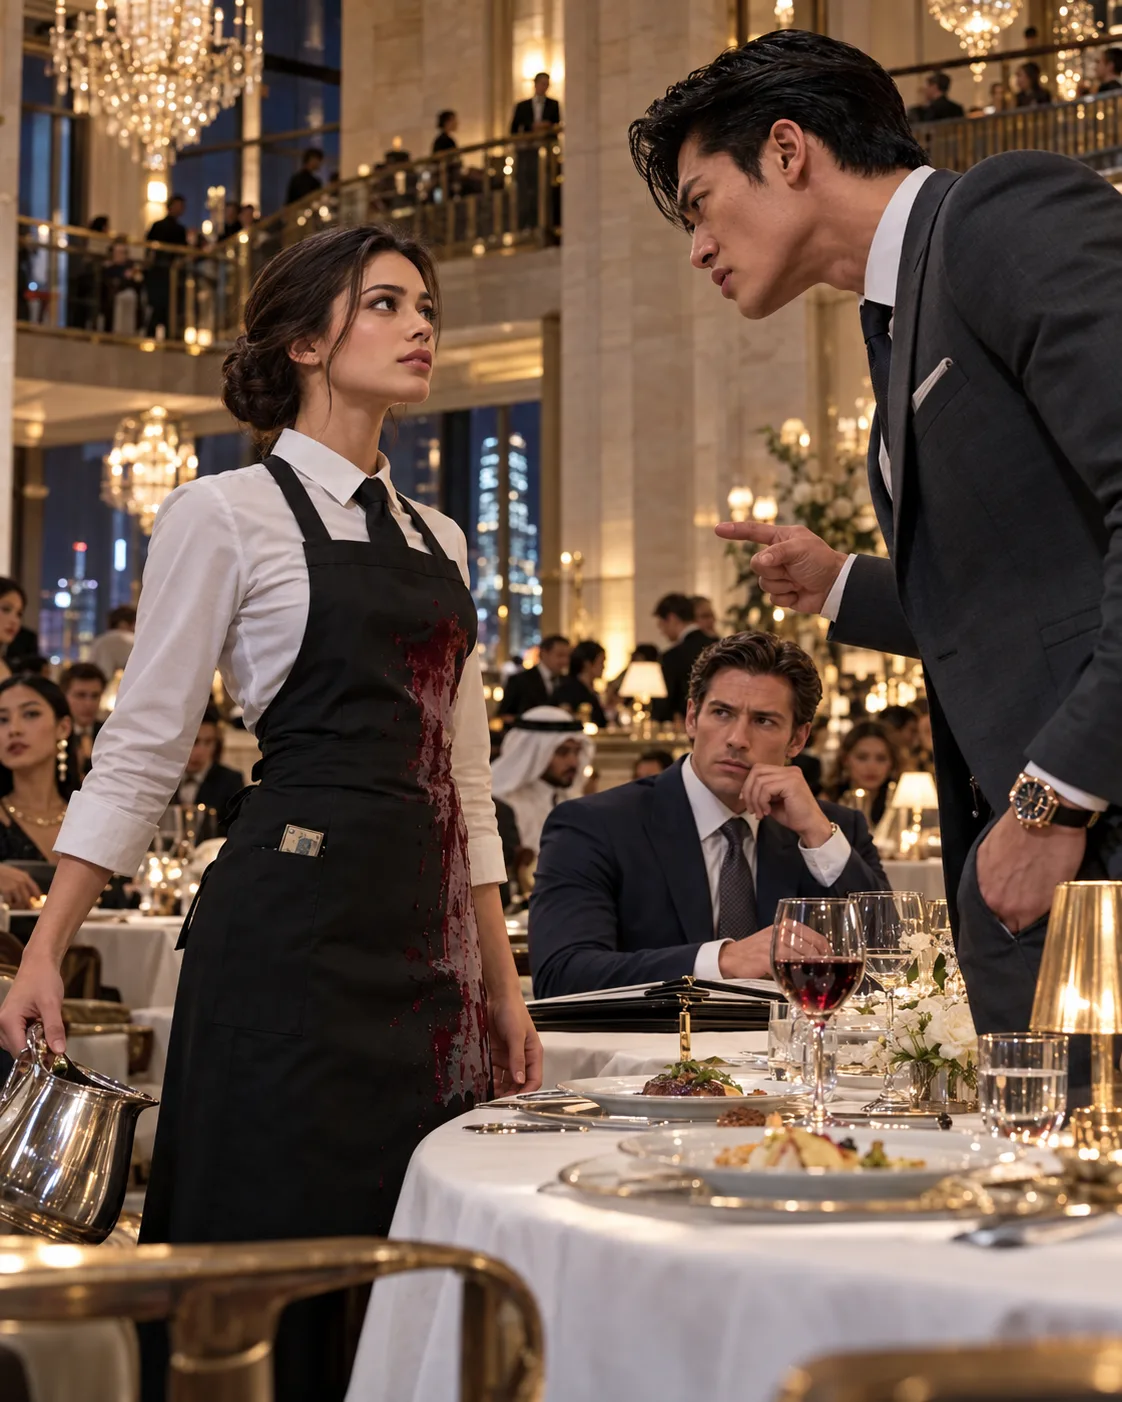
Alex Liang still had one weapon.
Time.
Callaway Urban’s refinancing deadline was approaching. If Everett could not replace the financing expected from the $1.4 billion sale, lenders could demand higher interest, additional collateral, or asset sales.
Alex understood leverage better than shame.
He offered a new deal.
The price remained $1.4 billion.
The Kensington parcel would be carved out temporarily while employee claims were resolved.
The remaining properties would close immediately.
Financial press called it a compromise.
Everett called it a trap.
“If we sell the cash-producing properties and keep Kensington with the debt,” he told the board, “we give Liang the good assets and keep the litigation.”
A director replied, “We may not have another choice.”
Serena had no vote.
She also had no patience for being used as a symbol in a financing decision.
When a reporter asked whether Everett should reject Alex’s revised offer, she said, “That is for his board and advisers. My concern is whether workers’ rights were concealed and whether I accurately reported what I heard.”
Lena approved.
“You are learning.”
“I hate that sentence.”
Behind the scenes, another possibility emerged.
The 2000 covenant did more than grant workers a share of redevelopment appreciation. Page seven—the page missing from Iris’s home copy but preserved in locker forty-two—required notice to a designated employee representative before any “material transfer undertaken in contemplation of redevelopment” and allowed beneficiaries to seek equitable relief for a transfer designed to defeat their rights.
The language was old and complicated.
But it gave Iris and other beneficiaries a basis to ask a New York court to prevent a closing that might prejudice the covenant before validity could be adjudicated.
Their lawyers filed a civil action.
They did not ask for ownership of the hotel.
They asked for a temporary restraining order preserving the property and records.
Alex’s lawyers argued the claims were stale, released, and barred by limitations periods.
The beneficiaries argued they had been concealed through a disputed satisfaction and could not reasonably discover the alleged fraud until now.
The judge did not decide the merits at the first hearing.
She issued a narrow preservation order: no transfer of the Kensington parcel pending an expedited hearing; no destruction or alteration of specified historical records; no representation that the employee covenant was conclusively extinguished.
It was not a final victory.
It was enough.
The revised Liang deal depended on certainty.
Certainty disappeared.
For the beneficiaries, the injunction created a different problem: legal victory required money. Expert title analysis, document review, and valuation work were expensive. Their counsel had taken the matter on a hybrid fee arrangement subject to court review, but costs still had to be advanced. Several workers worried that a long fight could consume whatever recovery might exist.
At a meeting in a union hall, one beneficiary’s son stood and said, “I don’t care about punishing rich people. My mother needs home care now.”
Another woman answered, “If we settle too fast, we sell everyone cheap again.”
The room grew tense.
Serena did not give a speech. She had no right to tell families how much uncertainty they should endure.
Iris finally said, “We need lawyers to show us choices with numbers. Not courage speeches.”
The room quieted.
That became the rule. Every major decision would be accompanied by plain-language estimates of time, risk, fees, and possible outcomes. Justice was not more honest because people were asked to suffer blindly for it.
That afternoon, Alex convened his own lenders. According to later-produced minutes, he argued that the beneficiary litigation was a nuisance that could be priced and settled. A credit officer asked the simplest question in the meeting: “What else was not disclosed?”
Alex had no satisfying answer.
Risk committees did not care about his humiliation at a restaurant. They cared that a hidden schedule, a related-party consultant, and disputed property rights had surfaced after months of diligence. Each discovery increased the possibility of another.
One bank reduced its proposed bridge commitment. Another demanded a broader indemnity. The economics of Alex’s acquisition began deteriorating before any court declared him wrong.
Serena found that almost anticlimactic.
“You mean a bank asking boring questions hurts him more than two hundred million views?” she asked Priya.
“Frequently.”
“I’m beginning to respect boring.”
“You should. Most durable accountability is extremely boring.”
That night, Everett called Serena. “We may have replacement financing.”
“Is it good?”
“No.”
“Is it survivable?”
“I think so.”
For the first time, survival no longer meant accepting Alex’s terms.
Then a second lender entered the picture.
A consortium led by a pension-backed real estate credit fund offered Callaway a twelve-month refinancing facility at a painful but survivable rate, conditioned on independent governance reforms and the sale of two noncore properties.
Everett’s company could survive without Alex.
Barely.
The board approved the financing.
When the news became public, Liang Meridian’s leverage collapsed.
That evening, Serena was eating noodles at Maya’s kitchen counter when Alex called her directly.
She stared at the number.
Lena had told her not to speak with him without counsel.
Serena let it go to voicemail.
He did not leave one.
He called again.
Then a text arrived.
You think this is justice. It is a negotiation. Everything is a negotiation.
Serena forwarded it to Lena.
She did not respond.
A second message came.
Your mother took money. Ask her what she signed in 2004.
Serena’s stomach tightened.
She turned toward Iris, who was washing a teacup at the sink.
“Mom.”
Iris looked over.
“What did you sign in 2004?”
May you like
The cup slipped in her hand but did not break.
That was answer enough.