Chapter 22 - THE BANK’S APOLOGY
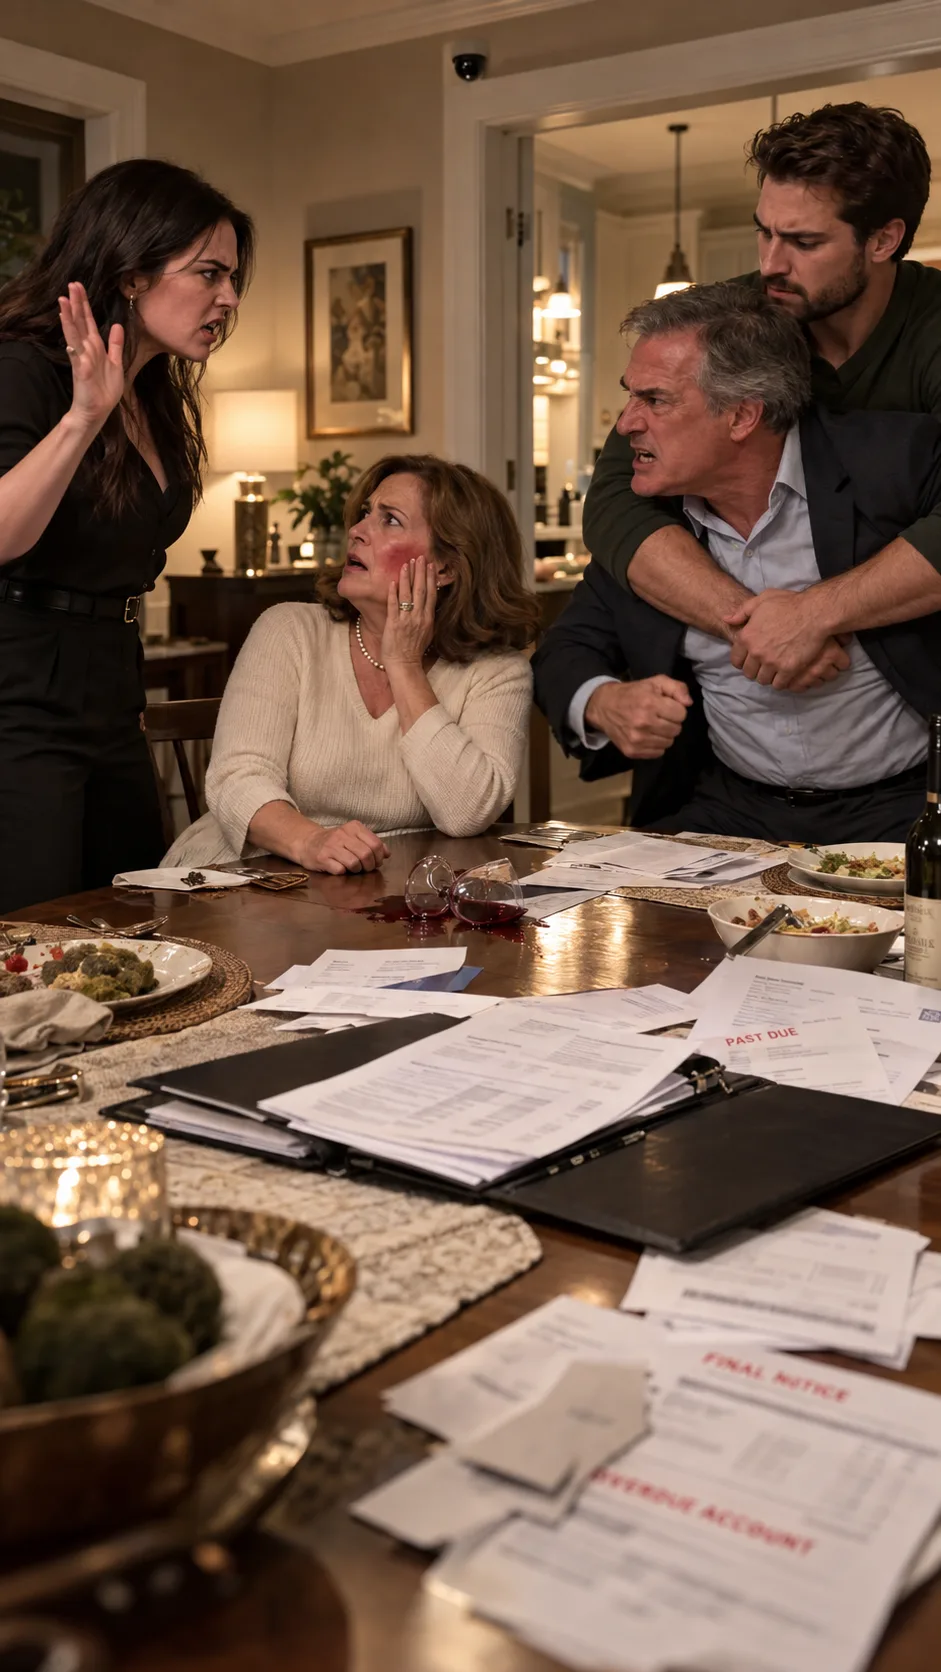
The bank dismissed its claim against me six weeks after my deposition.
The letter was written in careful corporate language.
After review of newly available information, the bank acknowledged substantial evidence that the guarantee was unauthorized and agreed that I had no liability.
At the bottom was an apology.
Two sentences.
I expected to feel vindicated.
Instead, I felt tired.
For months, my name had been attached to a $640,000 obligation created by my own son.
Two sentences could remove it from a bank’s file.
They could not remove the moment Linda asked whether there was anything else I had kept from her.
Still, the dismissal mattered financially.
Our retirement accounts were no longer threatened by the claim.
The bank also provided records under subpoena that strengthened the criminal case.
The forged guarantee had been uploaded through an online portal from Daniel’s home internet address.
Identity verification was completed using security questions drawn from my credit history.
One answer was my first mortgage lender.
Daniel knew it because I had once told him the story of buying our house at twenty-nine with a terrible interest rate and no air conditioning.
Another answer was my mother’s maiden name.
Family knowledge had become authentication data.
The realization bothered me more than the forgery.
At dinner one evening, Linda said, “We used to tell children not to talk to strangers. We never talked about what happens when the person misusing your information already knows your mother’s name.”
The bank offered free identity monitoring.
I laughed when I saw it.
Then enrolled.
Cedar Coast was restored under court supervision. The brokerage reversed part of the attempted liquidation, and insurers and financial institutions began negotiating responsibility for earlier losses.
One recovery hearing became unexpectedly personal. A lawyer asked Linda whether she had relied on the missing trust money for retirement.
“No,” she said.
“Then were you financially harmed?”
Robert objected before she could answer, but the question stayed with her.
Later she said, “It's strange how quickly people assume stolen money hurts less if you can survive without it.”
James had not created Cedar Coast because Linda was desperate. He created it because gratitude deserved form.
The theft was not smaller because we had other savings.
The full $184,000 was not immediately recovered.
Some had been spent.
Some had passed through too many accounts.
Some sat frozen in assets belonging to Bellwether and Argent Ridge.
Linda surprised everyone by refusing an early partial distribution from the trust.
Margaret asked why.
“Because I don’t need it right now.”
“It is yours.”
“I know.”
“James wanted you to have it.”
“I know that too.”
She thought for a moment.
“Then what do you want?”
Linda looked at me.
“I want it safe until this is over.”
For most of her life, money had been something Linda used to remove pain from other people.
School loans for a niece.
Rent for a cousin.
Daniel’s emergencies.
James’s old business crisis.
Cedar Coast was the first large sum that existed because someone wanted Linda herself protected.
Accepting that idea took time.
Meanwhile, the criminal case moved toward trial.
Celia eventually entered a plea to conspiracy and tax-related offenses after Naomi Price’s records made her position harder to maintain.
Marcus and Paula remained cooperating witnesses.
Melissa finalized her plea.
Daniel did not.
He rejected a proposed agreement.
His lawyers prepared to argue that he was an overwhelmed business owner manipulated by more experienced people, that Paula handled documents, Celia controlled Bellwether, Marcus controlled Arbor Vale approvals, and Melissa managed family records.
Everyone around Daniel, in other words, had done the parts that looked worst.
He had simply been in the middle.
Robert told me not to underestimate the defense.
“Complex fraud creates reasonable-doubt opportunities. Lots of hands. Lots of accounts. Lots of people with incentives to blame him.”
“I know.”
“You also have history with him. The jury won’t.”
“I know.”
“And James can’t testify.”
That one landed differently.
“No,” I said. “But his voice can.”
Robert nodded.
“If the judge admits the relevant portions.”
Around the same time, we attended a fraud-prevention session offered by the bank to customers affected by identity misuse. I almost skipped it out of professional pride.
Linda made me go.
“You investigated companies,” she said. “This happened inside our family. Sit down and learn something.”
The presenter described account alerts, verbal passwords, credit freezes, independent callbacks, and the danger of giving relatives broad access simply because they were relatives.
None of it was sophisticated.
That was humbling.
Afterward, an elderly man approached me because he recognized my name from the case. His daughter had opened cards in his name while managing his mail.
“I keep thinking I should have known,” he said.
I almost gave him a forensic answer.
Instead I said, “People who trust someone are not auditing them every morning.”
The sentence helped me too.
Nothing was guaranteed.
That became another lesson.
Evidence could be true and still face rules about how it entered a courtroom.
Emotion did not make it admissible.
Family history did not make it relevant.
A good case was not the same as an easy case.
One month before trial, prosecutors asked whether Linda and I would testify.
Linda said yes before I did.
After the meeting, I asked whether she was afraid.
“Of seeing Daniel?”
“Yes.”
“Very.”
“Then why so fast?”
May you like
She looked at me.
“Because fear has already made enough decisions in this family.”







